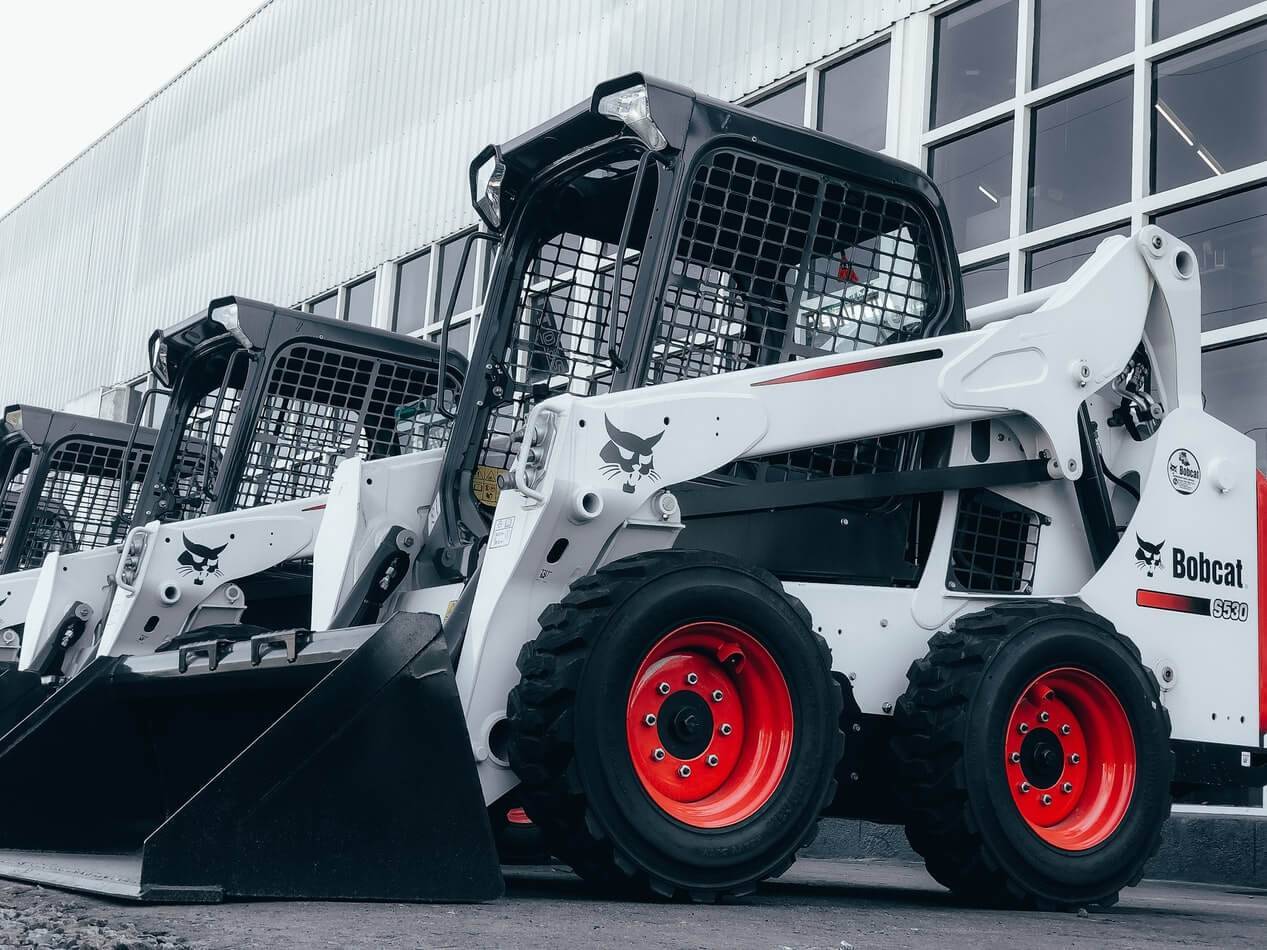

Every construction job comes with its own set of challenges—tight deadlines, shifting budgets, and the constant need for reliable material handling equipment. Without the right machinery, even the most well-planned projects can slow down, costing you time and money.
But here’s the thing: buying forklifts and other heavy equipment outright isn’t always the smartest move. It ties up cash that could be used for payroll, new contracts, or unexpected costs. That’s why many construction business owners turn to financing. Keeping your operations adaptable, competitive, and growth-ready is more important than simply keeping costs down. Let’s examine the most effective financing options for your equipment so you may continue to grow your company.
Exploring Financing Options for Material Handling Equipment

Purchasing material handling equipment outright can put a significant strain on your budget, especially if you’re managing multiple projects. Fortunately, financing allows construction businesses to acquire the necessary equipment while preserving capital for other expenses. Here are some common financing options:
1. Equipment Loans
An equipment loan provides a lump sum of money specifically for purchasing forklifts or other construction machinery. These loans usually require a down payment, and the equipment itself serves as collateral. This means you can get competitive interest rates while spreading out the cost over time.
2. Equipment Leasing
Leasing is an attractive option for businesses that need to upgrade their material handling equipment frequently. Instead of purchasing outright, you make regular lease payments, which can often be deducted as a business expense. At the end of the lease term, you may have the option to buy the equipment, renew the lease, or upgrade to a newer model.
3. Business Lines of Credit
A line of credit offers flexibility by allowing you to borrow as needed. If your construction business experiences fluctuating cash flow, this option ensures you can finance equipment purchases without tying up large sums of money at once.
4. SBA Loans
The U.S. Small Business Administration (SBA) provides loan programs that can help construction businesses finance forklifts and other heavy machinery. SBA loans typically come with favorable terms, including lower interest rates and longer repayment periods.
The Benefits of Financing Material Handling Equipment
Preserve Cash Flow
Keeping cash reserves available for payroll, unexpected expenses, and new project bids is crucial for business stability. Preserve cash flow by financing forklifts and other material handling equipment, allowing you to spread out payments and avoid a major financial strain.
Tax Benefits
Depending on your financing method, you may qualify for tax deductions under Section 179 of the IRS tax code, allowing businesses to expense the full purchase price of eligible material handling equipment, including forklifts, significantly reducing taxable income and improving cash flow.
Stay Competitive with the Latest Equipment
Construction technology is always evolving, and having modern material handling equipment can increase efficiency and safety. Financing makes it easier to upgrade equipment without large upfront costs.
Improve Credit and Business Growth
Successfully financing equipment and making consistent payments can strengthen your business credit. A strong credit profile opens up more financing opportunities in the future, helping your company grow.
How to Qualify for Equipment Financing

If you’re ready to finance forklifts or other material handling equipment, follow these key steps to improve approval chances, secure the best financing terms, and keep your construction business running efficiently with upgraded, reliable machinery that enhances productivity and cash flow.
- Check Your Credit Score – A strong business credit score can help you secure better interest rates and loan terms.
- Prepare Financial Documents – Lenders typically require business bank statements, tax returns, and profit-and-loss statements to assess your ability to repay the loan.
- Compare Lenders – Whether working with traditional banks, online lenders, or specialized financing companies, compare loan terms, interest rates, and repayment flexibility.
- Understand Your Business Needs – Choose a financing plan that aligns with your project timelines and equipment usage.
Secure the Best Financing with First Capital Business Finance
At First Capital Business Finance, we specialize in helping construction businesses across the U.S. secure financing for material handling equipment, including forklifts and other essential machinery. Our team works with business owners to find flexible, tailored solutions that fit their needs, offering competitive rates, fast approvals, and personalized service. Whether you’re expanding your fleet, upgrading to the latest equipment, or managing cash flow, we’re here to help you keep your operations running smoothly. Contact us today to explore your financing options and take your business to the next level!
Financial Disclaimer
The information provided is for educational and informational purposes only. The content on this website is not intended to be a substitute for personalized financial advice. Please consult a certified financial professional before making any investment decisions or financial plans. Any financial information presented is for general informational purposes and does not constitute financial or investment advice.