Excavator vs Backhoe Financing: Do Qualifications Differ?
If you’re trying to decide between an excavator and a backhoe, and you want to know how the financing differs before you commit, here’s the short answer: the qualification framework is the same for both machines. Lenders look at your credit, time in business, cash flow, down payment, and the condition and value of the equipment. What does change is how those factors play out in practice, depending largely on how much the equipment costs and what condition it’s in. This article breaks that down so you know what to expect when you go to finance either machine.
TLDR:
- Both machines use the same qualification framework: credit, time in business, cash flow, down payment, and equipment condition.
- The practical financing differences come from transaction size, not machine type. Full-size excavators cost significantly more than backhoes, which affects loan amounts, documentation requirements, and down payment dollars.
- Equipment age, hours, and condition affect the lender’s appetite for both machines. Neither type gets a free pass on collateral quality.
- If the decision between machines is still open, a First Capital advisor can help you understand what each transaction looks like before you commit to either
Looking to Finance A Backhoe or Excavator?
Call 888-565-6692 to speak with a financing specialist.

The Same Core Criteria Apply to Both
Lenders don’t underwrite a backhoe differently from an excavator because of what the machine does on a job site. Both are construction equipment. Both are used as collateral. Both financing applications will be evaluated on the same set of factors:
- Credit profile: personal credit history, any derogatory marks, and business credit history where it exists.
- Time in business: how long the company has operated, and whether that track record is documented.
- Business cash flow: recent bank statements showing revenue consistency and whether the business can support a monthly payment.
- Equipment condition and value: age, hours, working condition, and whether the asset can be clearly valued and titled.
- Down payment: your cash contribution, which reduces the lender’s exposure and can compensate for weaknesses elsewhere in the application.
The same credit tiers, same down payment logic, and same startup considerations that apply to backhoe financing apply equally to excavator financing. The programs that accommodate imperfect credit, limited time in business, or startup status work across both machine types.

Where the Financing Experience Diverges
The differences that actually show up in the financing process aren’t tied to which machine you’re buying; they’re tied to the transaction itself. Three variables tend to create different experiences.
Transaction Size Changes the Conversation
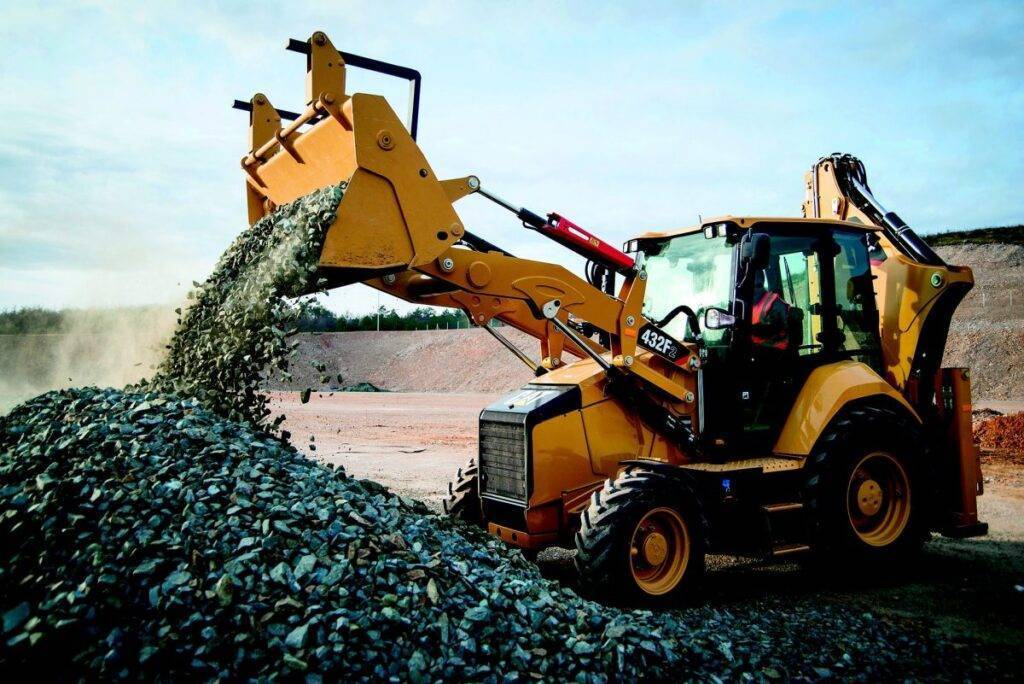
A used backhoe loader typically falls in a price range that many programs handle as a straightforward transaction. A compact or mini excavator can land in a similar range. But a full-size or large excavator, the kind used on commercial demolition, road work, or utility projects, can cost significantly more. That higher purchase price changes the financing in concrete ways.
- Larger loan amounts often receive more underwriting scrutiny, regardless of machine type.
- Some application-only programs have maximum financing amounts. Larger excavator purchases may push past those thresholds, requiring additional documentation such as business tax returns or financial statements.
- The down payment dollar amount is larger at the same percentage. A 10% deposit on a $40,000 backhoe is $4,000. The same rate on a $200,000 excavator is $20,000. The qualification tier may be identical; the cash required is not.
If you’re financing a compact or mini excavator at a price point similar to a backhoe, you’re unlikely to see any meaningful difference in how the transaction is handled. The divergence grows as the purchase price increases.
Equipment Age and Hours Affect Both
Age and hours are not backhoe-specific or excavator-specific concerns. Any lender financing used construction equipment will consider how old the machine is, how many hours it has logged, and what condition it’s in. This affects the collateral value the lender is willing to accept as security for the financing.
For either machine, older equipment with high hours may:
- Face program restrictions on eligible age or hours in some lender products.
- Require a higher down payment or shorter term to offset the collateral risk.
- Need a formal appraisal or equipment inspection for larger transactions.
A newer backhoe in excellent condition and a newer excavator in excellent condition will both be viewed more favorably as collateral than older, high-hour machines. The question to ask before applying is not “backhoe or excavator?” but “how does the specific piece of equipment I’m looking at hold up as collateral?”
New vs Used Adds Another Layer
Both machines are available new and used, and both can be financed either way. Used equipment financing for either type is common and widely supported. The variables that matter are the seller, the condition, and the documentation:
- Dealer vs private party: financing from a dealer typically involves cleaner paperwork (a formal invoice, clear title, known equipment history). Private-party purchases require more verification of title, condition, and seller identity, regardless of machine type.
- Title status: the equipment needs a clear, lien-free title to close. This is true for backhoes and excavators equally.
- Equipment value verification: lenders want to know the equipment is worth what you’re paying for it. An equipment guide value or formal appraisal may be requested for either machine on larger transactions.
Side-by-Side: How Qualification Compares
The table below summarizes where backhoe and excavator financing overlap and where the transaction details create different practical outcomes.

Making the Equipment Decision Alongside the Financing Decision
If you haven’t finalized which machine you’re buying, the financing side shouldn’t be the deciding factor between a backhoe and an excavator; the job requirements should. A backhoe is a versatile, lighter-duty machine well-suited for mixed work on smaller sites. An excavator, especially a full-size model, handles heavier commercial and industrial work where a backhoe would be undersized.
From a financing standpoint, the right question is: what does this specific machine cost, and what does my profile look like for that transaction size? A contractor financing a $45,000 compact excavator and a contractor financing a $45,000 backhoe loader are in nearly identical financing situations. A contractor financing a $250,000 full-size excavator is in a different one, not because it’s an excavator, but because of the size of the loan.
For specific payment examples for each machine type, visit the backhoe financing page and the excavator financing page. Both pages include program examples across different credit profiles and time-in-business scenarios.
Frequently Asked Questions
Does the type of equipment change what credit score I need?
No. Lenders don’t set different credit requirements for backhoes versus excavators. The same program tiers that apply to one apply to the other. Credit requirements vary by lender and program, not by machine category. What changes with a more expensive piece of equipment is that a lower credit tier may require a larger down payment in dollar terms.
Can I finance a used excavator or backhoe with a new business?
Yes, in qualifying programs. Both machine types can be financed by startup businesses when compensating factors are present, such as relevant industry experience, a meaningful down payment, and equipment with clear collateral value. Details vary by program. See construction equipment financing for more on how First Capital approaches startup applications.
Does buying from a private party vs a dealer affect financing for either machine?
Yes, for both. Dealer purchases typically involve cleaner documentation and a more straightforward lending process. Private-party purchases, whether a backhoe or an excavator, require more verification of seller identity, title, and equipment condition. Some programs limit private-party eligibility. If you’re considering a private-party purchase, ask your financing advisor which programs support it before making an offer.
What documentation is typically required?
For most construction equipment transactions, you’ll need a government-issued ID, business documentation, recent business bank statements, and a purchase invoice or equipment details from the seller. Larger transactions may require tax returns or financial statements. Requirements vary by program and loan size. [CONFIRM WITH FIRST CAPITAL for current documentation thresholds by product]
The Bottom Line on Excavator vs Backhoe Financing
Both machines are financed through the same programs with the same qualification criteria. The differences in the financing experience come from the transaction, specifically the purchase price, the equipment’s age and condition, and the documentation that the transaction size triggers. Whether you’re financing a backhoe loader or an excavator, imperfect credit doesn’t automatically prevent approval, and startup status doesn’t either, though compensating factors help.
If you’re still comparing machines or want to understand what either transaction looks like before you apply, a First Capital advisor can walk through both scenarios with you.