
Getting equipment loans for bad credit can feel overwhelming, but it’s entirely possible with the right approach. Whether you’re a startup or an established business with credit challenges, this guide will walk you through every step to secure the financing you need for your heavy equipment or machinery.
Many lenders understand that credit scores don’t always tell the full story. They now offer flexible loan options that focus on your business’s revenue, equipment value, and growth potential. With the right documentation and a strategic approach, even businesses with low credit scores can get approved and keep operations running smoothly.
Step 1: Understand What Equipment Financing With Bad Credit Means
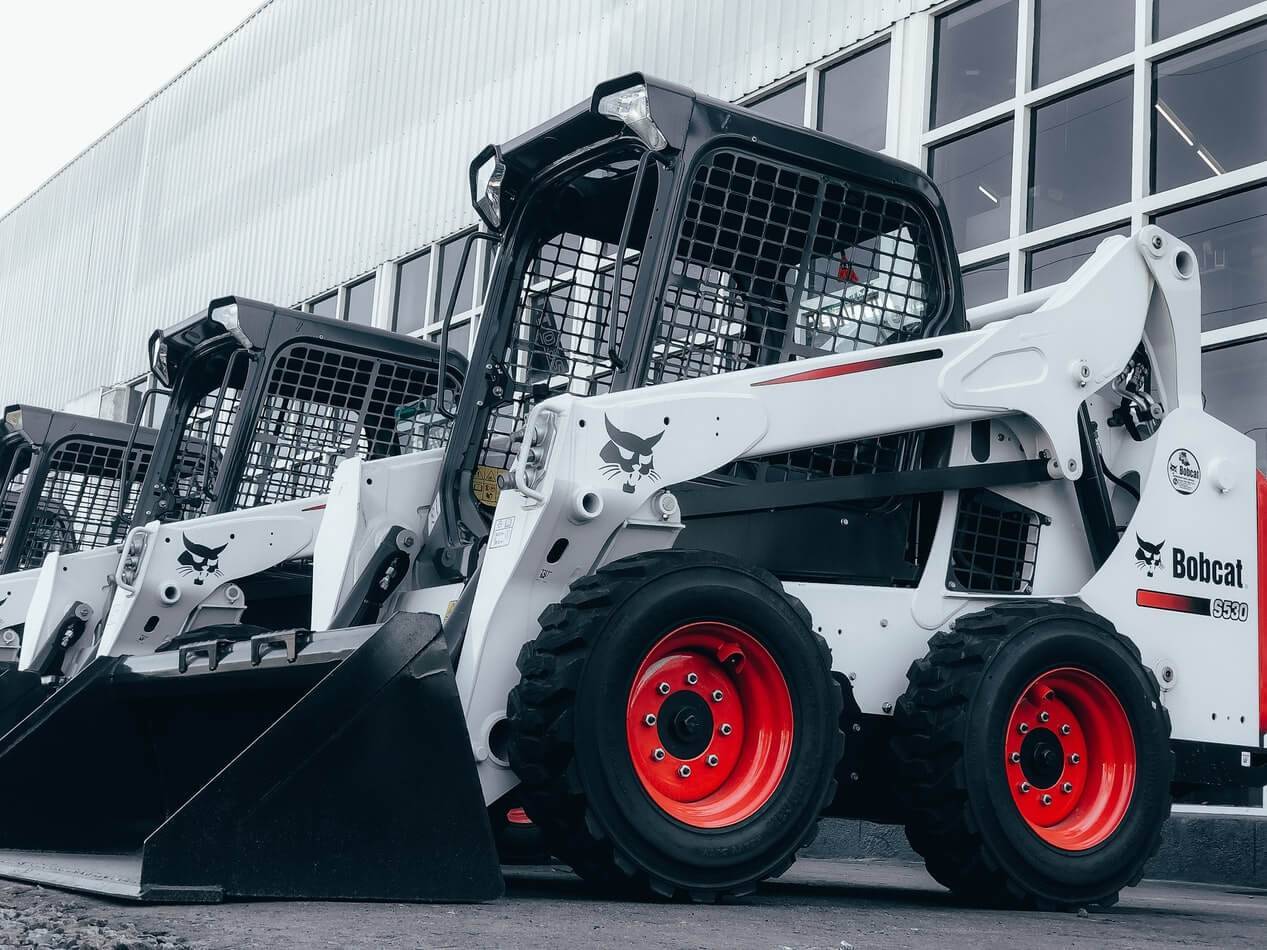
Equipment financing allows businesses to purchase or lease the equipment they need without paying the full cost upfront. When you have bad credit, lenders assess other factors such as your business revenue, time in business, or collateral. These equipment loans for bad credit are specifically designed to provide funding alternatives for business owners with low credit scores.
Types of Equipment You Can Finance
- Construction equipment
- Medical and dental machinery
- Trucking and transportation vehicles
- Manufacturing equipment
Step 2: Review Your Credit Profile and Business Financials

Even if you have poor credit, knowing your credit score helps you target the right lenders. Lenders also review your monthly revenue, time in business, and any existing debts before making a decision. Demonstrating consistent cash flow, maintaining updated financial records, and presenting a clear plan for equipment use can significantly improve your chances of approval.
What Lenders Look For:
- Minimum credit score thresholds
- Business revenue (often $10,000+ monthly)
- Length of time in operation (typically 6 months or more)
- Industry risk level
Step 3: Find Lenders That Offer Flexible Terms for Low Credit Scores
There are lenders that specialize in working with business owners with poor credit. These include alternative lenders and finance companies like startup equipment financing providers that don’t rely solely on credit scores. These lenders often consider factors such as collateral, business performance, and industry stability, offering more personalized solutions tailored to each business’s unique financial situation.
“Equipment financing can be a great option for businesses that need to upgrade or acquire new equipment but don’t have the capital upfront.” — U.S. Small Business Administration
Step 4: Prepare a Strong Loan Application Package
To increase your chances of approval, make sure your application includes a comprehensive and well-organized package that demonstrates your business’s stability and repayment ability. Lenders want to see more than just numbers—they’re looking for signs that your business is reliable, that you understand your financial obligations, and that the equipment you’re financing will directly contribute to your business growth. Gathering the right documents in advance not only speeds up the process but also shows lenders that you’re prepared and professional. Make sure your application includes:
- Bank statements
- Equipment quotes or invoices
- Business license and tax ID
- A brief explanation of your credit situation and how the equipment will help your business grow
Step 5: Consider Alternative Financing Options

If traditional loans don’t work out, try alternatives like:
- Sale-leaseback agreements
- Rent-to-own equipment
- Revenue-based financing
Step 6: Build Better Credit While Using Your Equipment
Using your new equipment to boost revenue can help you make timely payments, which in turn improves your credit score. As your business grows, you can eventually qualify for better financing terms in the future, leading to more favorable interest rates and larger loan amounts for continued expansion.
Bad Credit Doesn’t Have to Stop Your Equipment Financing Journey
At First Capital Business Finance, we understand that bad credit can be a hurdle, but it doesn’t have to derail your plans. We offer flexible equipment financing options designed to help businesses like yours thrive, regardless of your credit score. Let us help you secure the equipment you need today!
Financial Disclaimer
The information provided is for educational and informational purposes only. The content on this website is not intended to be a substitute for personalized financial advice. Please consult a certified financial professional before making any investment decisions or financial plans. Any financial information presented is for general informational purposes and does not constitute financial or investment advice.